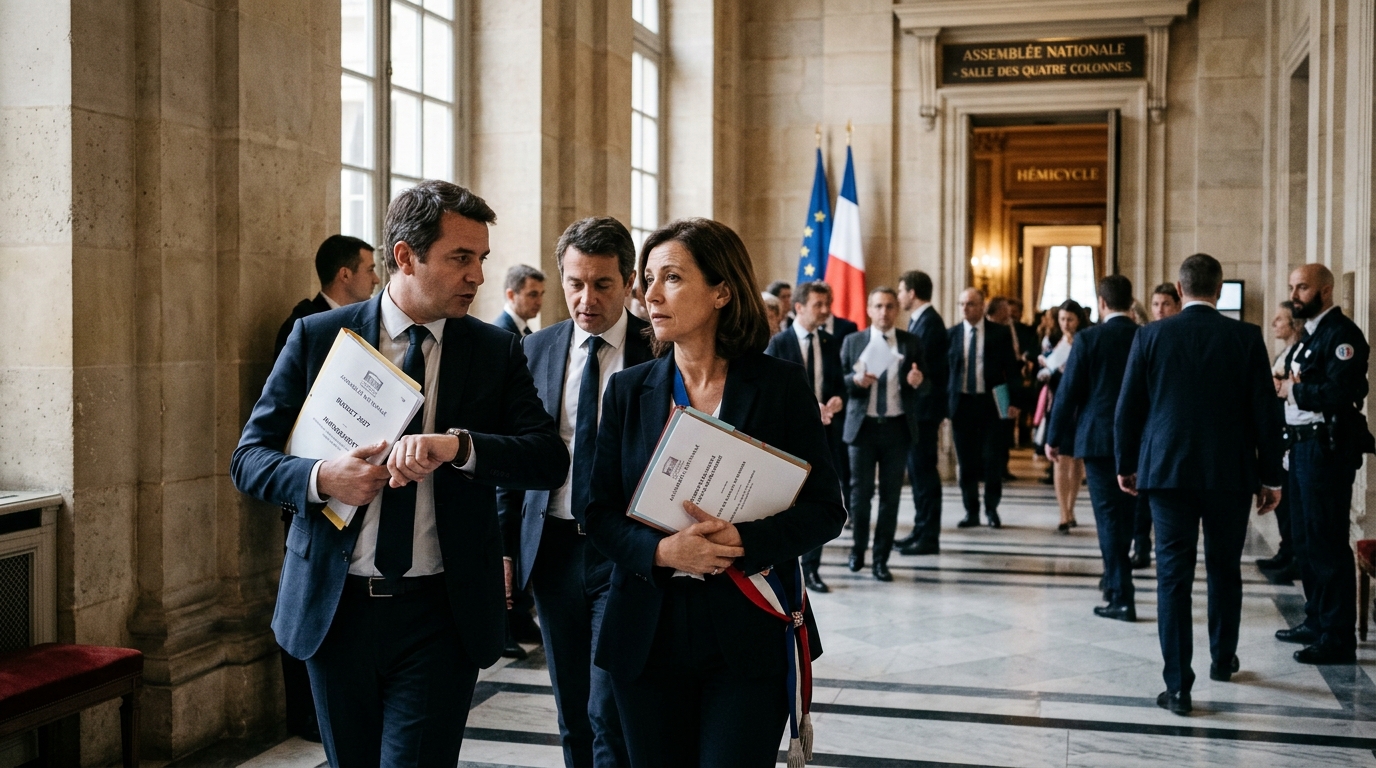
The solemn vote on the revenue half of France’s 2027 budget was supposed to happen October 20. Then it was October 27. Now the National Assembly has pushed it again, to November 3, after deputies were pulled onto the 2027 social security financing bill. What keeps slipping is not just a date; it is the government’s window to demonstrate that France can pass a budget through anything resembling normal parliamentary procedure.
The bond market is pricing that window as effectively closed. The French 10-year OAT yield hit 5.14% intraday on October 22, its highest since July 2002. As of October 26, the OAT/Bund spread stood at 156.4 basis points, with the 10-year OAT yielding 4.93% against 3.37% for the German Bund. That spread has moved from roughly the sub-100-basis-point area in mid-September, widening as global rates rose alongside Europe’s renewed energy shock and France’s own political risk stacked on top.
Since the late-summer move higher in global yields, 10-year OAT yields have risen more than Germany’s, as the energy shock and domestic unrest land on top of already-frail deficit politics.
Three Outcomes, Three Price Paths
The November 3 vote now replaces October 27 as the Assembly’s formal test of the revenue section, but the range of outcomes is unchanged. Call them passage, rejection, and the nuclear option.
A clean passage is the least likely path. Without a majority in the National Assembly, the government is unlikely to secure approval in a normal vote; the base case is that it uses Article 49.3 to adopt the budget without one, potentially after making concessions to ensure a subsequent no-confidence motion fails. Public Accounts Minister David Amiel has warned that amendments already approved would worsen the budget deficit by €10 billion. If a clean vote somehow passed with the deficit arithmetic intact, OAT yields would likely compress, though any specific “stabilized baseline” level should be treated as provisional in a market this headline-driven.
Outright rejection, which has precedent, is the market’s middle scenario. The National Assembly rejected the first part of France’s 2026 budget by 404 votes to 1 in November 2025, and the budget was ultimately adopted in definitive reading on February 2, 2026 after the government used Article 49.3 and survived no-confidence motions. A repeat rejection would still leave the government with procedural options, keeping the spread in a wide band while attention shifts to whether the Socialists again refrain from toppling the cabinet.
The Socialists, whose decision not to censure helped last year’s budget clear its final hurdle in early February 2026, are described as less inclined to do so this year. That asymmetry is the key risk. If a no-confidence vote is held and the government is defeated following a 49.3, the budget bill would be dropped and the next cabinet forced back to the drawing board. For OATs, that outcome pushes spreads wider still and tests whether the ECB moves beyond words.
Moody’s Held, But Only Conditionally
Moody’s maintained France’s sovereign credit rating at Aa3 and its outlook at negative on October 23, defying market expectations for a downgrade. The relief lasted about a session. Moody’s conditioned the affirmation on the assumption that a deficit-reducing budget for 2027 will be adopted, while also flagging that the sharp increase in public debt yields raises risks to France’s debt affordability.
France’s fiscal deficits have remained above 5% of GDP in recent years. Interest costs are expected to surpass €90 billion in 2027, and public debt, already at 119% of GDP at the end of June 2026, is moving toward the next uncomfortable handle in 2027 if consolidation slips again.
French Banks in the Crossfire
French lenders face heightened scrutiny when they present third-quarter earnings, with investors focused on sovereign spread sensitivity and risks from a potential economic slowdown. The broad issue is not whether the system is suddenly short of buyers, but how quickly higher yields and wider spreads can leak into bank funding costs and confidence, especially in a market primed to treat France risk as a bank factor.
The trade on France is not a prediction about November 3. It is a positioning question around three known pressure points: the vote itself, the S&P review scheduled for November 27, and the early-December constitutional deadline after which the government has additional fallback tools if the budget process stalls. Long-term investors are sitting out ahead of the elections, given budget uncertainty and the sensitivity of OATs to political fragility. Watch the Socialists. Watch the spread. The headline vote keeps moving; the interest clock does not.