There are oil companies cheaper than Petrobras. There are oil companies with more political stability. There are very few that combine record production, a forward price-to-earnings ratio below 5, and a dividend yield above 7% while reporting results after one of crude oil’s sharpest multi-session drops in years. That combination makes Tuesday’s Q3 release the most consequential moment for PBR shareholders in several quarters.
The Business
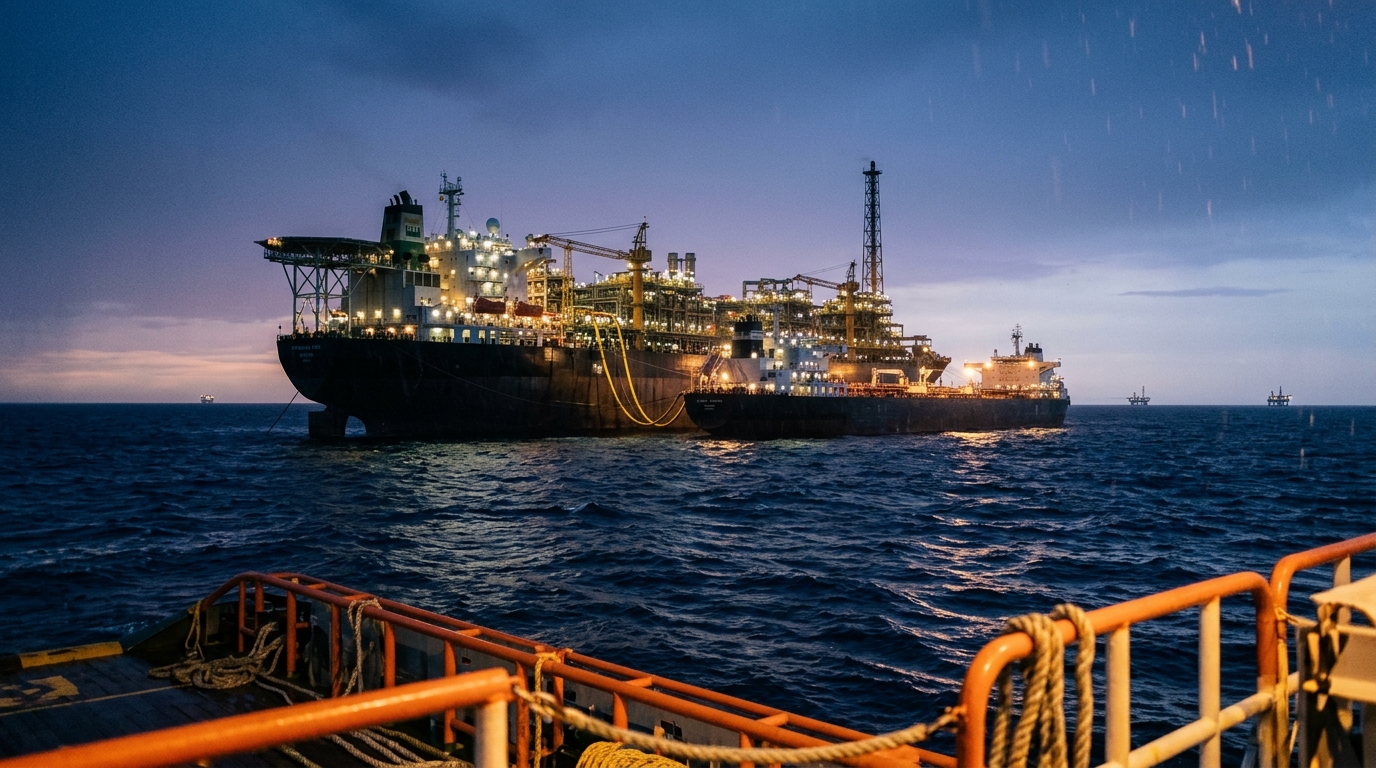
Petrobras is Brazil’s state-controlled integrated energy company, and its operational machinery has rarely run this well. The company reported record oil and gas production of 3.512 million barrels of oil equivalent per day in Q3 2026, up 11.7% year over year, driven by its Brazilian pre-salt operations. The strong performance came from the ramp-up of the P-78 and P-79 FPSOs in the Búzios field, lower losses from maintenance shutdowns, and the FPSO Alexandre de Gusmão reaching peak production at the Mero field. Refineries ran at 99% capacity utilization, diesel output hit a quarterly record of 769,000 barrels per day, and domestic refined product sales rose to 1.854 million barrels per day.
The company also set a record for crude oil and refined product exports at 1.251 million barrels per day. This is not a company struggling to find the oil. The question has never been volume.
Why Wall Street Is Paying Attention
Two catalysts have landed in the past two weeks. Citi added Petrobras to its 30-day upside catalyst watch list, citing a favorable operational outlook ahead of the earnings report. Meanwhile, 79% of analysts covering PBR rate it a Buy, with a consensus price target around $24.
What’s Driving the Opportunity
Petrobras reports Q3 2026 results on November 10, 2026, after the market close. The Zacks consensus is $1.23 per share on revenues of $31.3 billion. That implies roughly 33% revenue growth year over year. The bottom-line estimate has been revised modestly higher in the past 30 days, implying about 50% year-over-year earnings growth.
The valuation gap versus peers is stark. PBR trades at a forward price-to-earnings ratio below 5. The forward dividend yield is above 7%, with analysts’ one-year price target around $23.89. At $18.53, the stock is about 30% below its 52-week high.
What Could Go Wrong
Brent’s behavior last week is not a sideshow. Brent settled at $117.64 on October 30, 2026, then at $94.62 just three sessions later on November 4, 2026, a move of more than $23 that reset the revenue assumptions embedded in every oil producer’s valuation. At current spot levels near the high $90s, the Q3 numbers will reflect the stronger Brent environment that prevailed during the quarter, but the forward outlook suddenly looks more uncertain.
The larger risk is structural. A significant shift toward non-core business segments or domestic industrial projects may signal political influence overriding capital discipline, and dividend policy remains a flashpoint. History is instructive: in March 2024, Reuters reported that Petrobras paid only a routine dividend while setting aside roughly 43.9 billion reais in a fund for capital remuneration, a decision that blindsided investors and sent the shares down about 10% in a day. The current five-year plan estimates ordinary dividends in a range of $45 billion to $50 billion over 2026 to 2030, but it leaves extraordinary payouts to management and board discretion.
The Bottom Line
The operational case for PBR is as strong as it has ever been. Record output, refinery utilization near its ceiling, surging exports, and earnings-estimate momentum heading into Tuesday’s release. The valuation against peers is not a marginal discount, it is a chasm that only closes if investors trust the capital-allocation process.
That trust gets tested November 10, 2026. XP Investimentos has estimated Petrobras could distribute around $3.8 billion in dividends related to Q3 2026, above the roughly $3.4 billion paid in Q2. If management delivers a payout consistent with the 45% free-cash-flow policy and avoids signaling a drift toward politically directed spending, the discount to international peers becomes very hard to justify. If the dividend disappoints, Brent’s volatility gives traders all the cover they need to sell. The earnings webcast on November 11, 2026, at 9:30 AM ET is the moment that decides which direction this resolves.