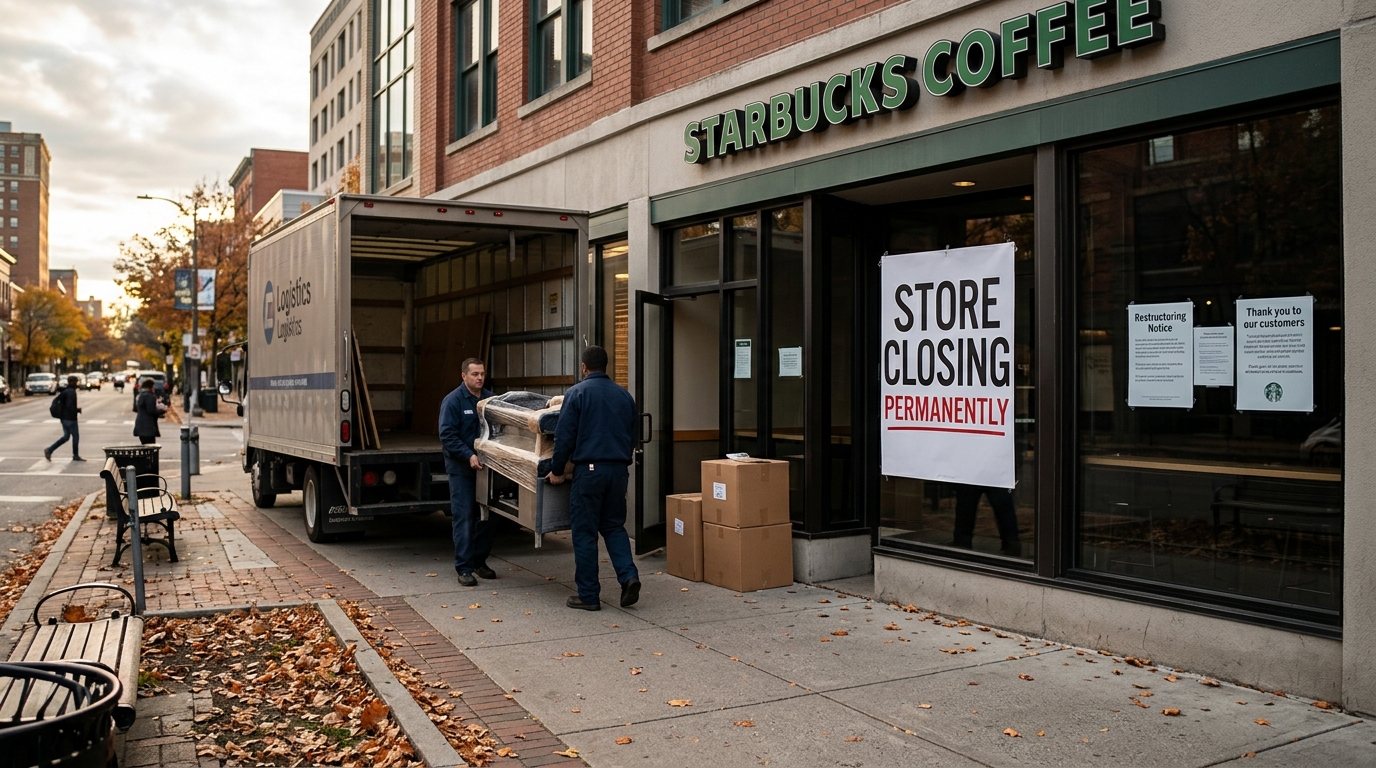
Starbucks is shutting roughly 250 North American coffeehouses later this week, in the final days of its fiscal year. The timing is not incidental. The company’s board approved the action on September 22, 2026, targeting locations that fail to meet brand expectations for experience and financial performance, with most closures and related charges expected by the end of fiscal 2026. Fiscal 2026 ends Sunday, September 27, 2026.
COO Mike Grams delivered the news in a message to employees, saying the locations targeted either are not delivering acceptable financial results or cannot provide the kind of experience Starbucks wants for customers and workers. There was no traditional press release. The regulatory filing was the market’s first signal.
Market Snapshot: SBUX
Starbucks shares were down less than 1% on Thursday, September 24, 2026. That muted reaction reflects two competing reads. Some bulls see portfolio clean-up of weaker locations. The counter-read: the charge lands in Q4 results, making the late-October report harder to model.
Stocks in Focus
SBUX: The company said it will incur about $300 million in restructuring charges with this round of closures, including about $200 million in cash charges primarily related to lease exit costs and employee separation benefits, and about $100 million in non-cash charges due to the disposal and impairment of coffeehouse assets. The company did not provide an update to its broader financial guidance, such as revenue, margin, or EPS targets, in this filing. That silence is where analyst estimates will move between now and late October.
For fiscal 2026, Starbucks is now projecting net new openings of about 440 cafes, down from its prior outlook of 600 to 650 locations, with the reduction driven by the North America closures and partially offset by higher net new openings in International markets. The 30%-plus reduction in unit-growth guidance matters to long-duration bulls who bid the stock up on Niccol’s expansion story.
It is the second big round of store closures under Niccol, who joined the company in 2024. Last September, Starbucks closed 627 stores, largely in North America, as part of its restructuring plan. Sequentially, 250 is smaller. But the financial context is different: Q3 comparable sales ran 7.9% globally, and Starbucks had raised its fiscal 2026 adjusted EPS guidance to a range of $2.55 to $2.65. The $300 million charge compresses what would otherwise have been a clean year-end result.
Peers to watch: CMG and MCD face no direct closure risk from this, but any sign that Starbucks traffic is being redistributed rather than lost could lift breakfast daypart reads. DNUT, which sells into Starbucks locations, has direct exposure to a shrinking North American store count.
Sector Watch
Quick-service restaurants have broadly held up through this rate cycle on the premise that value-oriented traffic is durable. Starbucks complicates that read. Its closures are not demand-driven; management is explicitly closing stores that do not meet its standards for experience and financial performance. Starbucks says it is accelerating its pace toward completing 1,500 coffeehouse uplifts. The bet is that a smaller, renovated footprint earns more per location. Whether that math shows up in Q4 guidance is the question traders should be pricing now.
Catalyst Calendar
- Starbucks FY2026 close, this weekend: A significant portion of the $300 million charge is expected to be incurred in fiscal 2026. Watch for any late-quarter disclosures.
- SBUX Q4 earnings, estimated late October: The next major catalyst for the stock arrives with the late-October 2026 earnings report. The guide for revenue and EPS is where the restructuring math gets tested against actual comparable-sales momentum.
The Cheat Sheet
- Top theme: Starbucks is shrinking to grow, but the $300 million bill arrives in Q4 results with no updated EPS guidance to anchor expectations.
- Stock to watch: SBUX into the late-October earnings report. The charge is known; the guide is not.
- Sector to watch: Quick-service restaurants, where Starbucks traffic data will inform whether closures redirect customers or simply remove them.
- Biggest risk: The company offered no revenue, margin, or EPS update alongside the closure announcement. Estimates will drift into the Q4 report, and that uncertainty is asymmetric to the downside in a week with thin catalysts.
- One thing to remember: A $300 million charge booked in the final days of a fiscal year is the definition of a known unknown. The late-October earnings report is the first clean look at whether Niccol’s portfolio discipline is actually accelerating per-store economics.