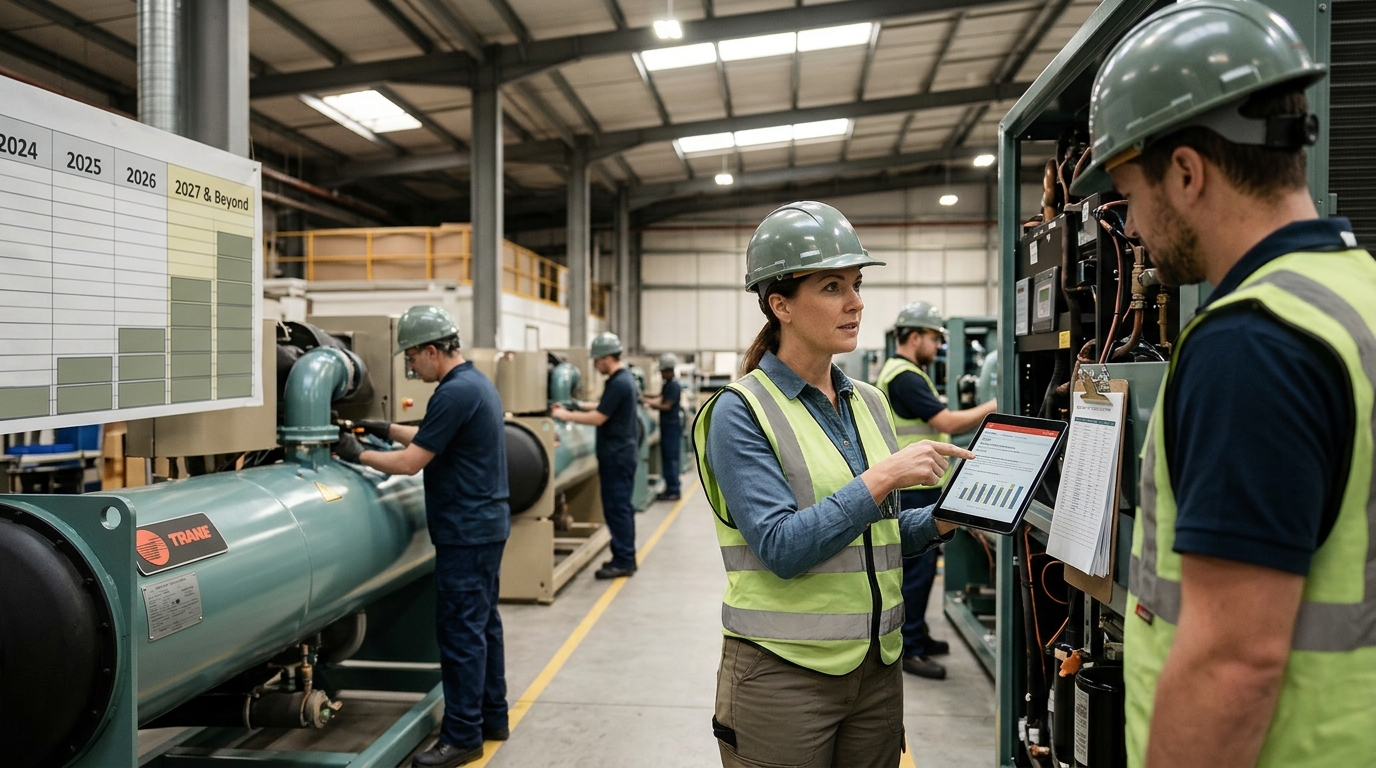
Most industrial companies talk about demand. Trane Technologies (NYSE: TT) has contracts for it. Global applied bookings rose more than 40% in the third quarter, pushing total backlog to $12.5 billion, and management said over $8 billion of that backlog is for 2027 and beyond. That is not a pipeline. It is a production schedule.
The Q3 results, reported October 29, were strong across every line. Revenue reached $6.76 billion, up 18% year over year, with organic revenue growth running at 16%. Adjusted EPS of $4.86 marked the sixth consecutive quarter of beating expectations. Management responded by raising full-year revenue guidance again, the company now expects full-year 2026 reported revenue growth of approximately 13.5% and organic revenue growth of approximately 11% versus 2025.
What makes this cycle different from prior HVAC upcycles is where the orders are coming from. Goldman Sachs, which upgraded TT to Buy on October 14, expects commercial HVAC suppliers to outperform residential manufacturers due to increased demand for large-scale systems driven by data centers, semiconductor plants, and AI infrastructure investments. That same note downgraded Lennox International to Neutral, a pointed signal that this is a commercial story, not a broad sector re-rating.
Trane’s book-to-bill ratio held at 107% in Q3, with backlog surging 73% year over year, particularly fueled by growth in the Americas Commercial HVAC segment. EMEA bookings rose 40% organically in the quarter, a detail worth noting, because it suggests the next leg of growth is not entirely dependent on the U.S. building cycle.
The investment angle here is less about this quarter and more about visibility. Free cash flow reached $2.83 billion year-to-date, up approximately 60%, giving management room to deploy capital without relying on debt markets. The risk is leaning too hard on a single growth-rate statistic. Trane has compounded earnings at a strong pace in recent years, but the exact five-year rate depends on the source and the measurement window.
The risk worth watching is margin compression. Management flagged supply chain, tariff, and foreign exchange risks even as it raised guidance. Adjusted operating margin slipped 40 basis points year over year in Q3, a modest drag that could widen if input costs accelerate into year-end. A strong dollar would also trim the EMEA and Asia Pacific contributions that are now gaining momentum.
Still, Trane enters Q4 with a backlog that most industrials would envy and a demand structure tied to two durable trends: energy efficiency mandates tightening globally and the build-out of compute infrastructure that runs hot and needs cooling. That combination does not reset between quarters. It compounds.