Four days after Salesforce held its Dreamforce Investor Day, the stock is trading around $240, roughly 34% below the all-time closing high it set on December 4, 2024. That gap is the argument.
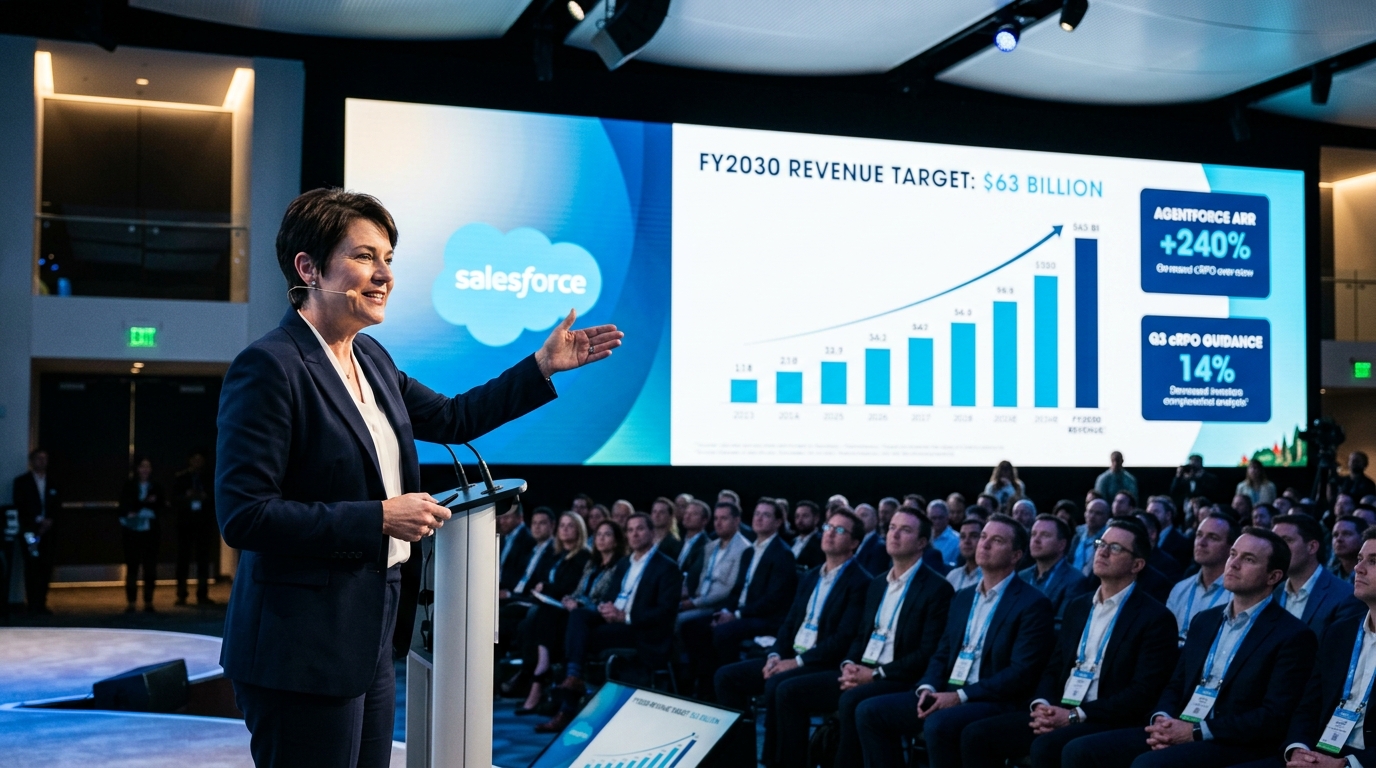
What happened September 16 was not the usual product showcase. Salesforce filed an 8-K the same day, attaching the investor presentation. Inside it: Agentforce annual recurring revenue exceeding $1.5 billion, up more than 240% year-over-year. The broader Agentforce and Data 360 combined ARR reached nearly $3.9 billion, up over 210% year-over-year. Agentic Work Units, the metric Salesforce uses to measure tasks its AI agents actually complete, hit 3.2 billion in Q2 alone, growing 97% quarter-over-quarter. These are not pipeline projections. Agentic Work Units are a usage metric. The ARR figures are the booked revenue.
The Business
Salesforce is the largest CRM platform on earth by revenue, with $41.5 billion in fiscal 2026 sales and a gross margin around 78%. What’s changed is the revenue model layered on top of that foundation. Agentforce lets enterprise customers deploy AI agents that handle sales, service, and operations tasks autonomously, billed by usage. Slackbot users grew over 150% quarter-over-quarter in Q2. Data 360 connected 104.3 trillion records in the same period.
The company also unveiled AIforce at Dreamforce, an AI-centric interface layer, alongside Agent Fabric, which Salesforce describes as a control plane for governing and orchestrating agents across a multi-vendor AI landscape. Salesforce is positioning itself as the orchestration layer, not a single-model vendor.
Why Wall Street Is Paying Attention
The post-Investor Day reaction from analysts was fast. Stifel raised its target to $300 from $275. Guggenheim moved to $300 from $270. Canaccord matched that move. JPMorgan called the event positive for the stock’s re-rating thesis. BNP Paribas analyst Stefan Slowinski came away, in his words, incrementally positive, citing accelerating new business activity and expecting revenue reacceleration to begin in Q3.
For Q2 FY2027, Salesforce reported a 34.1% non-GAAP operating margin. Full-year FY2027 revenue guidance was raised to $46.1 to $46.4 billion. Q3 current remaining performance obligation growth guidance was set at approximately 14% year-over-year, a metric that directly signals future revenue. The $63 billion FY2030 revenue target was reaffirmed.
What’s Driving the Opportunity
The core case is operating leverage meeting product momentum. At around $240, CRM trades at roughly 22x trailing earnings against an average analyst target near $275, with Stifel and Guggenheim sitting at $300. The company has delivered 7.0 billion Agentic Work Units to date across Agentforce and Slack. The company has also said it has closed over 29,000 Agentforce deals since launch, with more than 60% of Q4 FY2026 Agentforce bookings coming from existing customer expansion. Cross-sell at that scale carries higher margins than new logo acquisition.
Q3 FY2027 earnings are scheduled for December 1. The setup heading into that report is simpler than it looks: does cRPO come in at or above the guided 14%? If it does, the re-rating thesis the analysts are writing about becomes a financial fact, not a projection.
What Could Go Wrong
The stock has a habit of rewarding analyst upgrades with brief pops before giving them back. Earlier in 2026, major buy calls from JPMorgan and Citi each produced an initial move that faded. The pattern only broke after Q2 FY2027 results confirmed the Agentforce numbers. Pricing and adoption uncertainty remain real. Salesforce CEO Marc Benioff has warned publicly that AI cannot become “social media 2.0,” suggesting execution risk is on his mind. Competition from Microsoft Copilot and other enterprise AI platforms is not theoretical. The 5.4x EV-to-NTM recurring revenue multiple is not cheap for a company growing revenue in the low double digits.
The Bottom Line
The Dreamforce numbers gave analysts something concrete to upgrade around, not just a product vision. Agentforce ARR more than tripling in a year, usage growing 97% sequentially, and a 14% forward cRPO guide together tell a story about monetization that the stock price has not yet priced. With Q3 earnings on December 1, investors have roughly ten weeks to decide whether the discount to the all-time high reflects real risk or a sentiment overhang that the numbers are already dissolving. Both answers are defensible. The asymmetry favors those who read the 8-K before the crowd did.