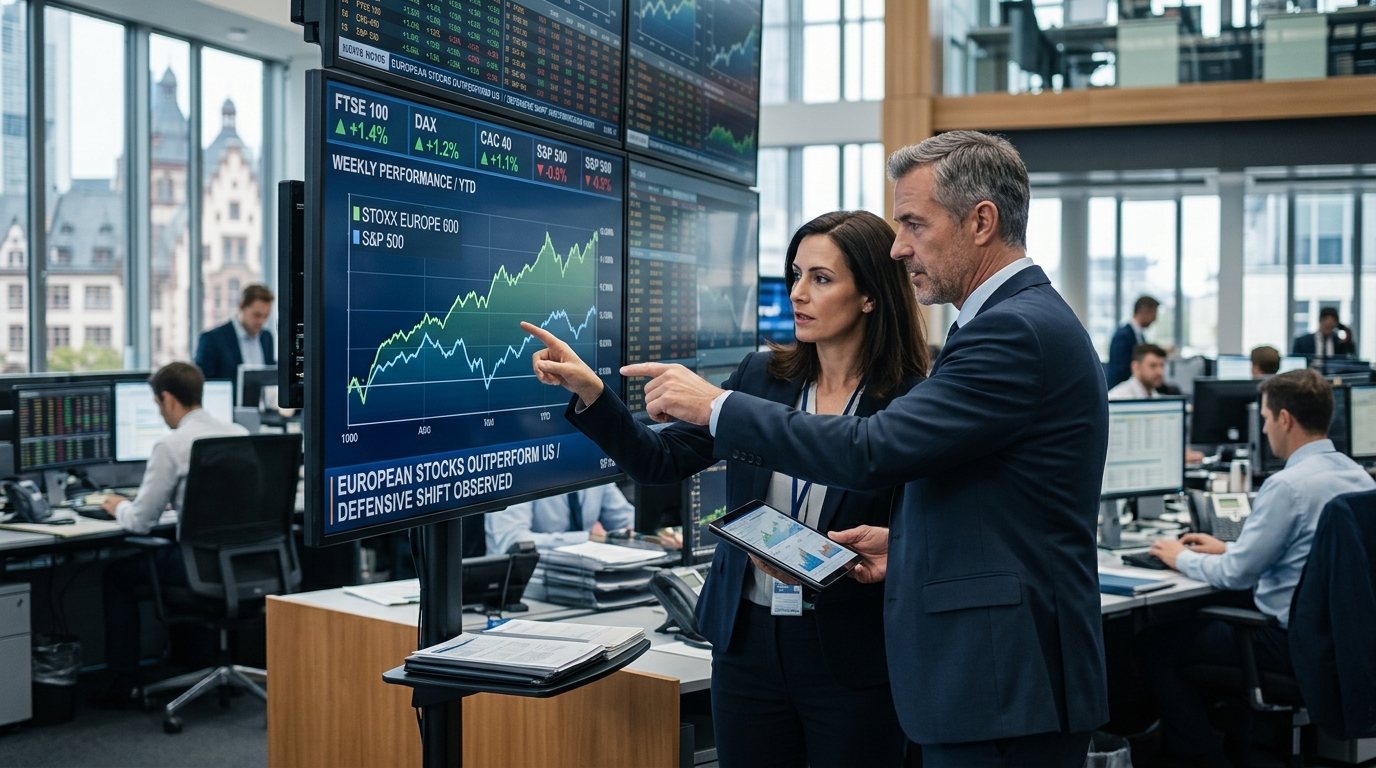
The question landing in every asset-allocation meeting this morning is straightforward and genuinely hard to answer: is Europe’s sudden outperformance of the S&P 500 a durable shift, or just what happens when a crowded trade cracks for a week?
European stocks are headed for their biggest weekly outperformance over the S&P 500 since March, as the region benefits from a switch among investors out of the AI trade and from some positive earnings news. Thursday’s closes told the story in numbers: the FTSE 100 finished up 1.04%, the SMI gained 1.49%, and the CAC 40 added 0.78%. The S&P 500, by contrast, spent most of this week absorbing bruising losses in the names that led it higher all year.
Why the AI Trade Cracked
Global technology stocks sold off sharply, as a growing list of worries, including rising borrowing costs and tougher competition from China, caused traders to sour on AI investments. The financing angle matters most. According to Baird tech strategist Ted Mortonson, the sell-off in AI-related stocks is increasingly about who needs financing and what that financing costs. Tech stocks from New York to Seoul were rattled after hot US inflation data stoked fears of further Federal Reserve rate hikes, hitting companies that rely on debt to fund AI infrastructure build-out.
Europe’s index composition is precisely what makes it a natural shelter in this environment. European equities appear well-positioned to capture reflationary tailwinds given their cheaper valuation, lower crowding, and easier earnings comparisons, without being overly dependent on the fate of the AI trade. That structural point is not new. What is new is the market finally acting on it.
The Earnings Argument
The second leg of the bull case is timing. Europe’s third-quarter reporting season is just opening, and expectations are high. Barclays strategists expect European earnings to have jumped 21% in the third quarter, partly boosted by a weaker euro, with the team led by Emmanuel Cau saying “resilient hard data and positive pre-announcements suggest third-quarter estimates remain within reach and beats are likely.”
Barclays frames the moment this way: with recent jitters around AI, oil, and rising rates, this season is a chance for “equities to connect back to fundamentals.” Morgan Stanley is equally constructive: the bank raised its MSCI Europe target for June 2027 to 2,840, implying about 12% upside, on the back of higher projected earnings per share. Goldman Sachs Research has also upgraded its full-year view, lifting its forecast for top-down EPS growth in the STOXX Europe 600 to 15% from 10%.
The Bear Case Is Real
Institutional investors who have heard this argument before are right to be skeptical. Barclays strategists expect the global equity market to face more restrictive financial conditions as the monetary easing cycle draws to a close, with the equity bull market “arguably running on tighter margins” as the prospect of renewed monetary tightening reduces support from lower interest rates.
The combination of rising oil prices, higher bond yields, and renewed fiscal uncertainty affected European equities during September, following gains earlier in the summer. France remains a specific concern, with fiscal worries returning in recent weeks. And there is the awkward intra-European divergence visible even today: the FTSE 100 was down less than 0.1% in early trading on October 16, while the DAX was up about 1% and the CAC 40 was up about 0.2%. A rising tide, it is not.
What the Debate Is Really About
The deeper question is whether the US technology complex is experiencing a temporary correction or the beginning of a multi-quarter derating. Deutsche Bank strategists, among others, have pulled back on their recommendations for the tech sector, with Deutsche Bank strategists on October 9 saying the rotation into tech had “run far and the risk-reward no longer looks favorable in the near term.”
If AI spending growth decelerates even modestly, European defensives and financials benefit structurally, not just for a week. European banks, for example, have considerably outperformed the Magnificent Seven group of US mega-cap stocks since 2022. That is the hidden argument underneath the weekly performance numbers.
Stocks to Watch
Stoxx Europe 600 broadly is the clearest expression of the rotation. Financials and industrials led Thursday’s session, with industrials gaining 0.7% and among the top gainers on the index.
Schneider Electric provided some of Friday’s positive sentiment, with the industrial heavyweight lifting the broader European mood heading into the weekend.
European banks remain the most structurally interesting beneficiary. Higher-for-longer rates in Europe hurt sovereigns but support net interest margins at institutions from BNP Paribas to Barclays itself.
SMI constituents deserve a closer look after Switzerland’s index put up the strongest Thursday performance in the region. The Swiss benchmark’s defensive tilt, weighted toward healthcare and consumer staples, is exactly what investors are paying up for right now.
One week does not confirm a rotation. But investment committees that dismissed European equities as structurally inferior to US tech are this week confronting a question that will not go away quietly: what happens to the S&P 500’s premium if AI capex financing costs keep rising?