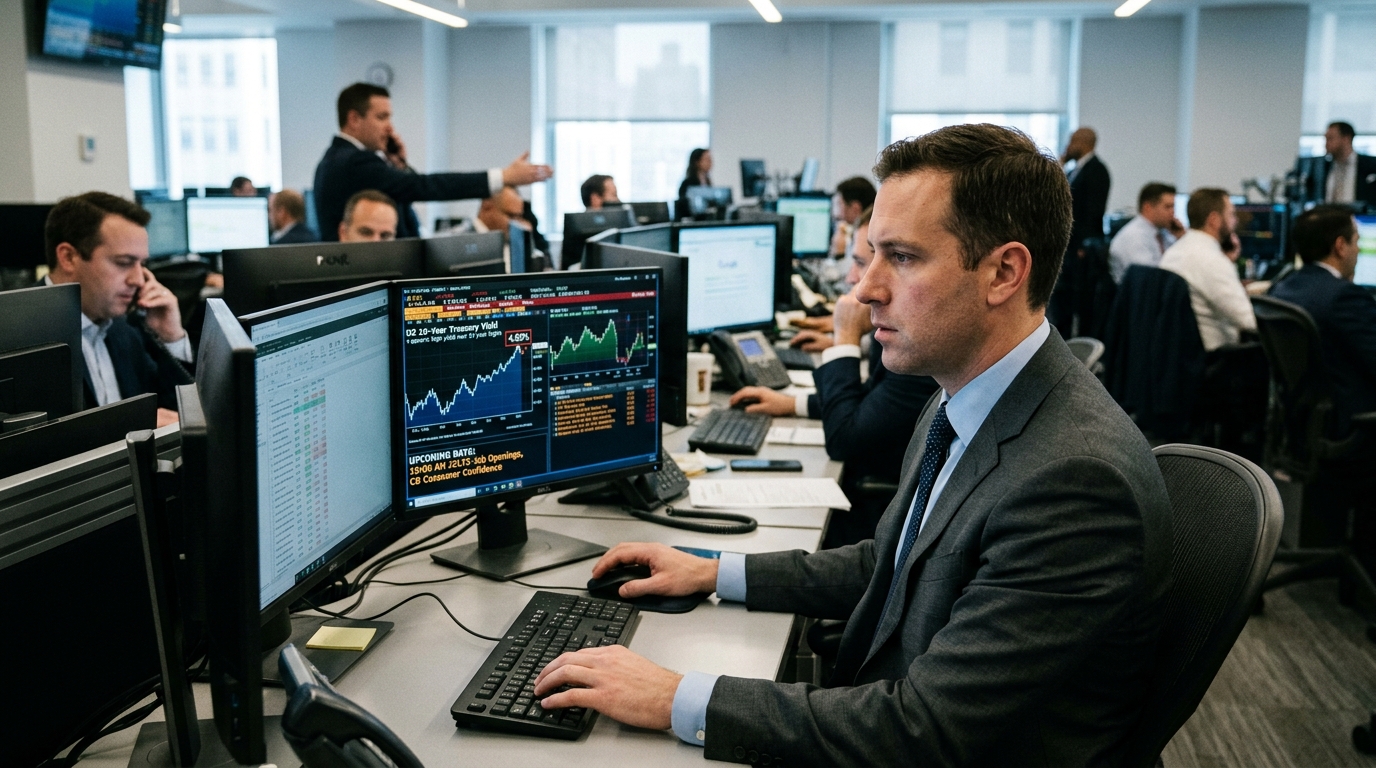
Two numbers land at 10am Eastern this morning and both carry real consequences for how traders position into the most crowded Fed decision in years. August JOLTS job openings and the Conference Board’s September consumer confidence index drop simultaneously, opening a week that ends with August PCE on Wednesday and September payrolls on Friday. The bond market has already rendered a verdict. Now the data has to answer back.
Where yields stand
U.S. Treasury yields rose sharply on Monday amid sustained selling pressure, pushing the benchmark 10-year to about 5.23% and sending the long bond back toward the mid-5% range. As of Monday’s close, the 30-year sat at 5.56%. The 10-year’s rapid climb above 5% reflects how quickly investors’ expectations have shifted toward additional tightening from the Federal Reserve in light of stubborn inflation. TLT, the long-duration bond ETF, closed Monday at $78.51 after trading as low as $78.27.
What the data means for October
Prediction markets put a quarter-point hike at roughly 69% for the October 28 FOMC meeting, with a hold around 31%, as of this morning. That pricing is fragile. A strong JOLTS number, say openings above the 7.23 million consensus forecast, reinforces the argument that labor demand remains too hot to pause. July’s reading showed employers posted slightly more openings, with the total ticking up to 7.271 million from a revised 7.182 million in June. A second consecutive upside surprise would push October hike odds higher and send TLT lower still.
The confidence reading is the sharper instrument today. August confidence came in at 89.4, unexpectedly lower, missing the 90.3 forecast. More telling than the headline: the Expectations Index fell to 68.2 in August, staying below the recessionary 80 threshold. September consensus is 90.1. A print above 92 would suggest the consumer is holding up despite 5%-plus mortgage rates and $93 crude, and it hands Warsh cover to hike. A print below 87 sharpens the internal contradiction in the current cycle: the labor market says yes, the forward-looking consumer says no.
The sentiment backdrop
The weekly mood reading Friday underscores why confidence matters so much right now. The University of Michigan’s Index of Consumer Sentiment fell to 48.1 in September, its lowest reading in four months and down 15% from January 2026, as rising inflation fears and a deteriorating outlook for business conditions weighed on households. The twelve-month inflation outlook climbed to 4.6% from August’s 4.0%, the steepest mark since June and a sharp departure from the 3.4% level that prevailed earlier this year. When consumers are pre-loading inflation expectations at that pace, the Conference Board’s forward-looking questions become a direct read on whether those fears are bleeding into spending plans.
The key trades
SPY finished Monday near $765.61, sitting just above a support cluster with overhead resistance at $772-$775. Despite the S&P 500 hovering near all-time highs, Morgan Stanley Research highlighted a notable decline in market breadth that may prompt either a pullback or a catch-up rally in lagging stocks. A hawkish 10am data combination, strong openings plus a confidence beat, extends the yield selloff and puts SPY’s support to an immediate test. TLT, already through technical support, has limited floor in that scenario.
The more interesting opportunity is in the asymmetry. Soft JOLTS plus a confidence miss hands the market a brief window to price a November skip, which would squeeze rate-sensitive sectors sharply higher. Homebuilders and regional banks, both punished by the yield surge, would be first to react. That trade has a short shelf life: PCE arrives Wednesday and payrolls Friday, and neither is expected to be friendly. But from now until 10am, the positioning opportunity is real.
Fed Chair Kevin Warsh has argued that the central bank has a role to play in preventing inflationary pressures from broadening out, and his refusal to offer forward guidance means each data release carries outsized weight. Today’s 10am print is the first hard test of a week that will define whether the Fed hikes at the October 27-28 meeting or waits for December. Watch the Expectations component inside the Conference Board number. It is the one sub-index the bond market will care about most.